

Is your turnover approaching CHF 100,000, or are you launching a business that should exceed that amount in its first year? Check your Swiss VAT registration obligations now. Waiting until you close the accounts without reviewing your forecasts can leave you funding VAT that you never charged your customers.
You register with the Federal Tax Administration (FTA). Before completing the application, establish whether you must register, when your liability begins and which VAT accounting arrangements fit your business.
At a glance
- The ordinary threshold is CHF 100,000 of relevant worldwide turnover, not profit.
- Supplies exempt without credit must be distinguished from supplies exempt with credit, such as qualifying exports.
- A new business must assess its first twelve months of expected activity; VAT liability can begin from day one.
- Notify the FTA within 30 days of the start of your VAT liability.
- Voluntary registration below the threshold can be useful, but run the numbers first, especially if your customers are private individuals.
Read feedback from entrepreneurs supported by Entreprendre.ch.


Who must register for VAT in Switzerland?
Your legal structure alone does not determine the answer. A sole proprietorship, LLC (Sàrl/GmbH), limited company (SA/AG) or association can be liable. What matters is the business activity, relevant turnover and type of supplies you make.
For the ordinary threshold, supplies made in Switzerland and abroad count unless they are exempt without credit under Article 21 of the VAT Act. A business invoicing mainly overseas customers should therefore not assume that the threshold is irrelevant.
A special CHF 250,000 threshold applies to qualifying non-profit sporting or cultural associations run on a voluntary basis and public-benefit institutions. It does not apply to every association.
Exempt supplies: with or without input tax credit?
Certain healthcare, education and insurance supplies are exempt without credit, subject to specific conditions. The profession described on your website is not enough to decide the treatment: one business can have several types of supplies with different VAT consequences.
A supply exempt with credit, such as a qualifying export, is treated differently from a supply exempt without credit. That distinction affects both relevant turnover and the right to recover input VAT. Our article on Swiss VAT explains how these mechanisms work.
When does your Swiss VAT liability begin?
You are starting a new business
Assess whether the circumstances indicate that you will reach the threshold during the twelve months following the start of activity. If so, liability generally begins from the outset. Do not wait for the invoice that takes turnover past CHF 100,000 before considering VAT.
For example, signed contracts covering CHF 150,000 of relevant supplies in your first twelve months call for an immediate assessment, even if no customer has paid you yet.
Your business is already operating
For an established Swiss business that has so far been exempt from registration, that exemption generally ends at the close of the financial year in which relevant turnover reaches the threshold. This is different from a new activity, where the first twelve months of forecasts are decisive.
Example: an established business has a 31 December year-end. Without starting a new activity or undergoing a structural expansion, it generates CHF 120,000 of relevant turnover in 2026. In this ordinary case, VAT liability starts on 1 January 2027 and the business must notify the FTA within 30 days. Taking over a business or opening a new business sector can change the assessment. See the FTA’s rules on the start of VAT liability.
If the starting date is unclear, give the FTA your dates, turnover figures and forecasts. The date you submit the application and the date your liability begins can differ. A late application does not automatically postpone the tax obligation.
Should you register voluntarily below the threshold?
This is primarily a commercial decision. Under the effective method, a registered business can recover eligible input VAT on purchases. It must also account for VAT on sales and meet the associated filing obligations.
If your customers are mainly businesses entitled to deduct VAT, adding it to your prices is often less of a commercial issue. For private customers, it increases the final price or reduces your margin if you keep the same VAT-inclusive price.
A worked example for a consulting business
You invoice CHF 80,000 excluding VAT for services at the standard rate and incur CHF 10,000 excluding VAT of fully deductible purchases. Output VAT would be CHF 6,480 and deductible input VAT CHF 810, leaving CHF 5,670 payable before any other transactions.
Now consider private customers, keeping the total final selling price at CHF 80,000 and the same purchases of CHF 10,000 excluding VAT, invoiced by the supplier at CHF 10,810.
| Simplified annual calculation | Not registered | Voluntarily registered: effective method |
|---|---|---|
| Total paid by customers | CHF 80,000 | CHF 80,000 including VAT |
| Revenue excluding VAT | CHF 80,000 | CHF 74,005.55 |
| VAT on sales | None in this example | CHF 5,994.45 |
| Purchase cost after recoverable VAT | CHF 10,810 | CHF 10,000 |
| Margin before other expenses | CHF 69,190 | CHF 64,005.55 |
Under these assumptions, registration reduces the margin by CHF 5,184.45. Figures are calculated from unrounded amounts and rounded to the nearest centime. The example assumes all sales are subject to 8.1%, all purchase VAT is deductible and there are no other VAT effects. It excludes administration costs. Recovering CHF 810 of input VAT therefore does not offset the VAT funded out of unchanged customer prices.
Significant startup investment can make voluntary registration attractive. A business with few purchases and mainly private customers should pay particular attention to its final prices. Being VAT-registered is not an official certification of business quality.
Choosing your VAT accounting arrangements
Effective method or net tax rate method?
Under the effective method, you calculate VAT on your supplies and deduct eligible input VAT. Investment and the proportion of deductible purchases therefore directly affect the balance payable.
Under the net tax rate method, where approved for your circumstances, you apply the assigned rate to turnover including VAT. Input VAT is allowed for on a flat-rate basis; you do not deduct it again invoice by invoice. Customer invoices still show the statutory VAT rate for the supply, not your approved net tax rate.
Compare the methods using a representative financial year, planned investment and the rules for changing methods. The lowest-looking rate is not enough to identify the best option.
Agreed or collected consideration?
These arrangements determine when transactions are reported: generally when invoiced under agreed consideration, or when paid if accounting on collected consideration has been authorised. The choice must work with the way you keep your accounts.
How often do you submit a VAT return?
The effective method normally involves quarterly returns; the net tax rate method normally involves half-yearly returns. Special arrangements also exist. Since 2025, businesses with annual turnover no higher than CHF 5,005,000 can apply for annual reporting, subject to conditions. Advance payments are required: annual reporting does not mean paying VAT only once every twelve months. The FTA’s annual VAT reporting page explains the conditions and timetable.
Returns are submitted through the FTA’s online services. Use the current portal rather than an old tutorial referring to “VAT Return easy”, a service that is no longer available.
What to organise immediately after registration
Update quotation and invoice templates, software tax rates, advertised prices and VAT accounts. Review transactions around the registration date: these may require specific treatment, as may existing stock and investments.
Set up a filing and payment calendar and keep a cash reserve. Many common VAT mistakes arise from one incorrect setting repeated across every invoice, rather than an isolated calculation error.
If relevant turnover falls below the threshold and is expected to remain below it during the following tax period, deregistration can be requested no earlier than the end of the relevant tax period. The FTA must receive the request within 60 days after that period ends; otherwise, the business is treated as remaining voluntarily registered. A cessation of business activity must instead be notified within 30 days. Final adjustments may be necessary. These deadlines are set out in the FTA’s rules on the end of VAT liability.
Our accounting team can compare methods and organise your first returns using your accounting figures.
Register at the right time and organise your VAT
Assess your relevant turnover and start date before completing the application. Compare methods using your actual customers and costs, then update your Swiss invoice templates and reporting calendar. Check your VAT number and registration status once the FTA confirms registration.
Frequently asked questions
Should I wait until I have received CHF 100,000 before registering?
No. Relevant turnover and the rules governing the start of liability determine registration. A new business must consider its first twelve months of forecasts.
Can VAT obligations arise below CHF 100,000?
Yes, through voluntary registration or particular obligations. Buying certain services from abroad can trigger acquisition tax even without ordinary VAT registration.
Is VAT registration different in Geneva and Vaud?
VAT is federal. The basic rules and the FTA authority are the same. Your activity and transactions matter more than the canton where you operate.
Can I recover all VAT on my purchases?
No. Entitlement depends on how the purchases are used, the type of supplies you make and your accounting method. Registration does not make private expenses deductible.
Sources and updates
- FTA — principles of value added tax (in French).
- FTA — VAT liability.
- FTA — online registration and useful documents.
- FTA — VAT accounting arrangements.
- FTA — annual VAT reporting.
- FTA — submitting VAT returns.
English editorial review: 22 September 2026. Key registration rules and official references checked against the FTA’s current information.

Romain Prieur is a Swiss-qualified chartered accountant and founder of Entreprendre.ch. Drawing on more than ten years of experience in audit and supporting Swiss businesses, he advises entrepreneurs on company formation, accounting and taxation.



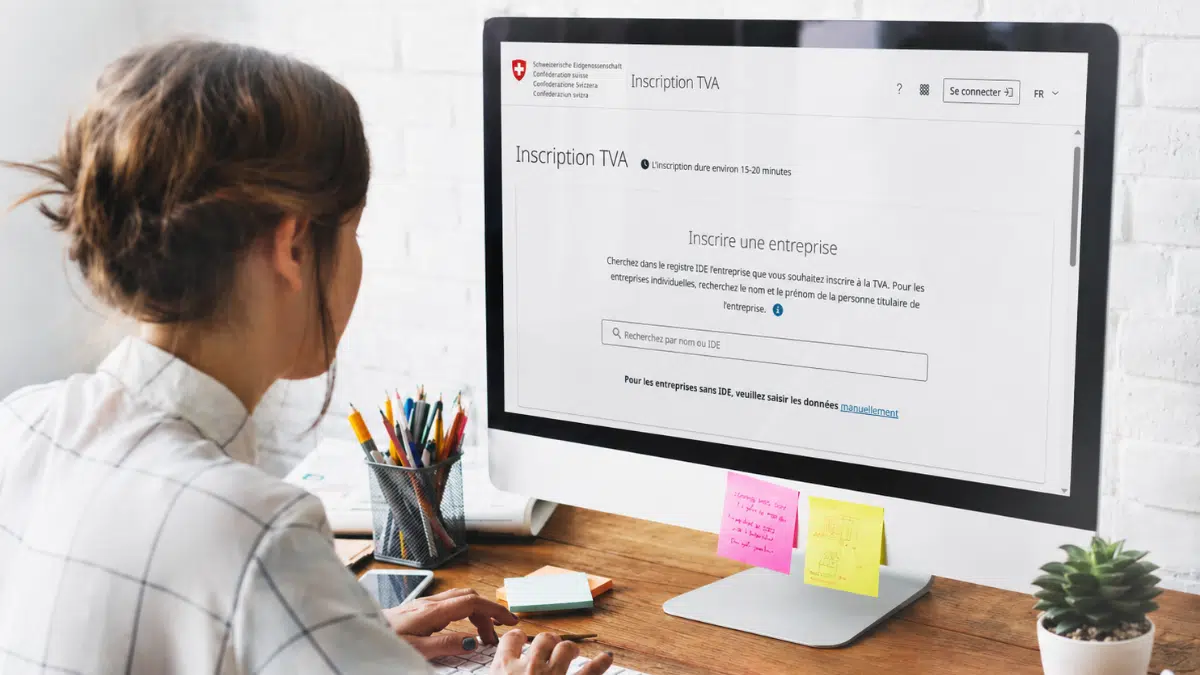
How do you register for Swiss VAT?
Start with the official VAT registration page. Prepare the business details, activity description, contact information, UID where available, and forecast or historical turnover.
For certain legal structures, including sole proprietorships, the AHV/AVS social security number is requested. An existing business should have the relevant accounting figures ready. A foreign business must review the tax representation rules and any requirements specific to its situation.
A commercial register extract can help you complete the application, but a list of useful documents is not a universal legal requirement: not every business liable for VAT is necessarily entered in the commercial register.
Check the information before submitting it. The FTA states that you cannot directly amend a submitted application form. Keep the confirmation and PDF of your application, then check the response, particularly the effective date and accounting arrangements.
Registration activates the relevant VAT status of your UID. To understand the format or check another business, read how to find and verify a Swiss VAT number.